What Is a Virtual Account for Crypto, and Should You Use One?
A virtual account turns converting money into a bank transfer. That convenience is real, and so is the fact that there is no order to cancel.
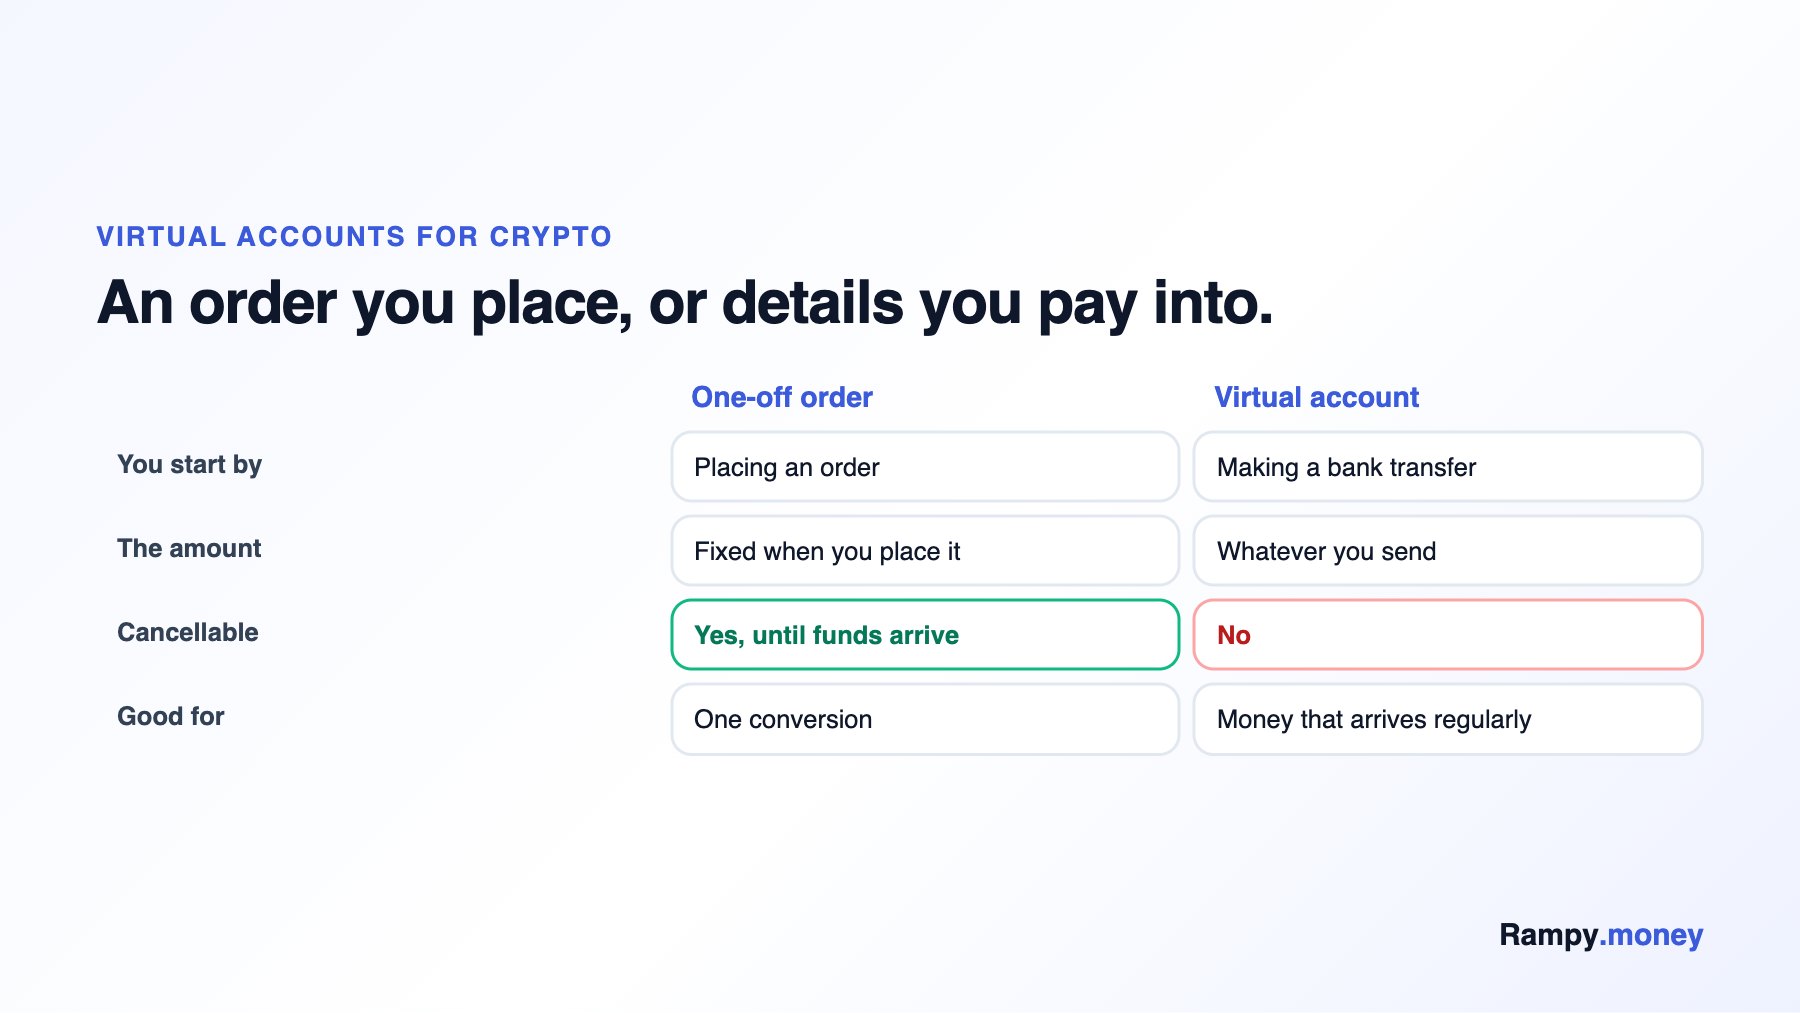
A virtual account — sometimes called a deposit account — is a set of bank details issued in your name that exist to be converted. Money paid into them is turned into stablecoin and sent to your wallet automatically, with no order to place. It is the difference between filling in a form every time and simply making a bank transfer.
How it differs from an ordinary order
| One-off order | Virtual account | |
|---|---|---|
| You start by | Placing an order for an amount | Making a bank transfer, whenever |
| The amount is | Fixed when you place it | Whatever you send |
| Cancellable | Yes, until funds arrive | No |
| Our price | 1.99% + 1.99 below 500, then 0.99% + 1.99 from 500 | 1.99%, no fixed fee |
| Good for | One conversion you are thinking about | Money that arrives regularly |
The pricing is genuinely different, not just marketing
A one-off order costs a percentage plus a fixed amount. A virtual account is a flat percentage with no fixed part. That structure means the account is cheaper on small amounts, where a fixed fee dominates, and dearer on large ones. With our numbers — 1.99% + 1.99 below 500, then 0.99% + 1.99 from 500 against 1.99% — the order becomes the cheaper one at 500. Below that the account is cheaper; from there, the order is.
This is worth doing the arithmetic on rather than assuming. Nobody should pay more for convenience they do not need.
The risk that has no undo button
This is the single most important thing to understand before opening one, and it is the reason we do not offer them as the default. An ordinary order gives you a moment between deciding and committing. A virtual account removes that moment deliberately, which is exactly what makes it useful for recurring payments and exactly what makes it unforgiving for one-off ones.
Minimums you should respect even though nothing enforces them
We ask that deposits be at least 100 at a time. Unlike an order minimum, this cannot be enforced: there is no request to reject, because the money has already arrived by the time we hear about it. Send less and it will still be converted, it just costs proportionally more, because the network fee to deliver the stablecoin does not shrink with the amount.
One account per currency
A virtual account is issued in a currency, on a rail — a GBP account on Faster Payments, a EUR account on SEPA, a USD account on ACH and wire. You can have one in each currency switched on for your account; the verification page lists them under Where you can be paid. Who may pay into each one differs by currency, and the rules are worth reading first: see who can pay into a deposit account.
Who should actually use one
- Freelancers and agencies converting a predictable amount each month.
- Businesses that would rather put permanent details on an invoice than place an order per payment.
- Anyone whose salary or recurring income arrives in fiat and is meant to end up in stablecoin.
And who should not: anyone converting once, anyone still deciding, and anyone who would be materially hurt by an accidental double payment. For those, an ordinary order and its cancel button are worth more than the convenience.
A Rampy deposit account is issued in USD, EUR or GBP, converts at 1.99% with no fixed fee, and sends to the wallet you nominate.
Open a deposit accountFrequently asked
Can I cancel a payment into a virtual account?
No. The account converts whatever arrives as it arrives, so there is no pending order to cancel. This is the main trade-off against placing an ordinary order.
Can I have accounts in more than one currency?
Yes: one in each currency switched on for your account, USD, EUR or GBP. The verification page lists them under Where you can be paid.
What happens if I pay in less than the minimum?
It is still converted. The minimum is a published request rather than an enforced rule, because the money has already moved by the time we see it. Small deposits simply cost proportionally more.
Is a virtual account cheaper than a one-off order?
Below roughly 500 it is, because it carries no fixed fee. Above that the one-off order is cheaper, because its percentage is lower. Do the arithmetic for the amount you actually move.